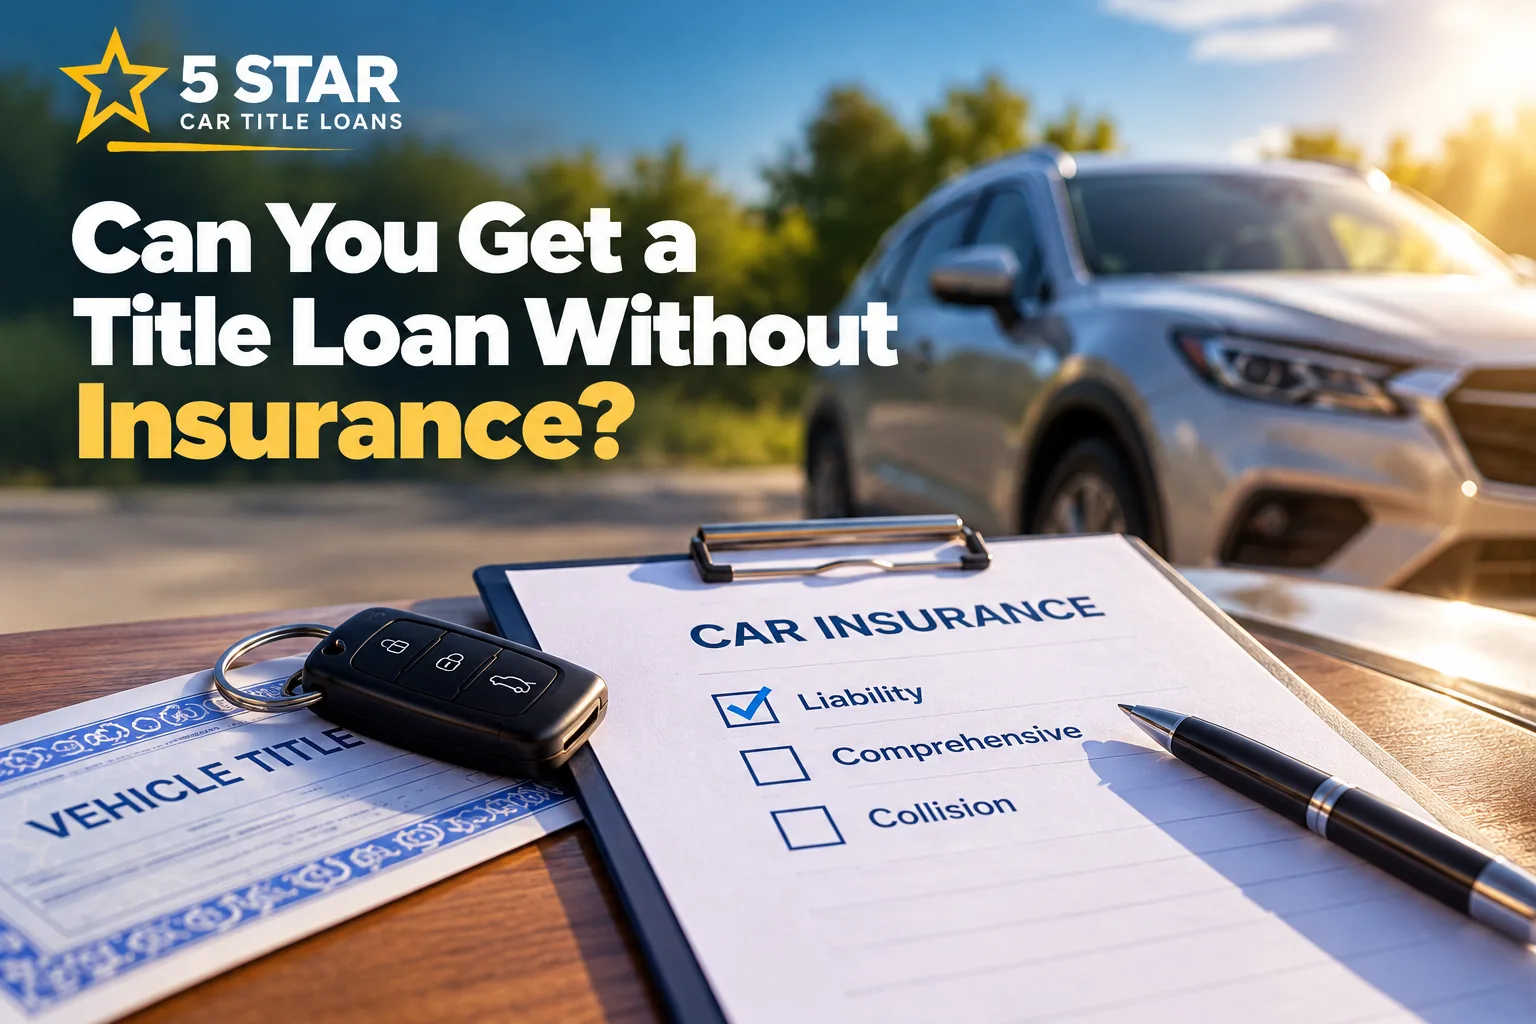
Yes, you may be able to get a title loan from us even if you have no car insurance or only liability coverage, depending on your situation. Liability pays only for damage you cause to others.
Most of our title loans require full coverage insurance, which also pays to fix or replace your own car in case of a crash, theft or storm, but we may make exceptions.
Borrowing a smaller amount compared with your car’s value, or having a strong, steady income, may improve your chances of qualifying for a title loan without full coverage, because the loan carries less risk for us.
You can apply and get a free loan estimate without full coverage insurance.3 If your loan requires it, you can arrange the coverage before you sign your loan agreement.
Editorial Disclosure: 5 Star Car Title Loans™ is a licensed direct lender, NMLS ID 2253575. This guide is for informational purposes only and is not financial advice. Your loan approval, amount, APR and terms depend on your state’s law, your car and your income.
Key Takeaways
- Full coverage is usually required. That means comprehensive and collision on your policy, not liability insurance alone.
- Exceptions are possible. Ask us before you buy a policy, because some loans are approved without full coverage.
- Apply first, insure second. Once you pre-qualify, we tell you if your loan needs full coverage.
- Keep any required coverage active. Your policy must list us as lienholder and loss payee until your loan is paid.
- Know the risk. Our APRs go up to 150%, and never above the cap your state’s law sets.7 Missed payments can cost you your car.9
Do You Need Insurance to Get a Title Loan?
Yes, on most of our loans, and many other title loan companies have the same requirement.
This is because your car is the collateral for the loan, which means it secures what you borrow.
If it is damaged in an accident, stolen or declared a total loss, full coverage pays to repair or replace it. That protects both you and us.
The same insurance rules apply to any vehicle you borrow against, including trucks, SUVs, vans, motorcycles and RVs.
What Does Full Coverage Mean?
A full coverage policy has three parts, and each one pays for something different, as the Texas Department of Insurance explains:
| Coverage | What It Pays For | Needed for Your Loan |
|---|---|---|
| Liability | Injuries and damage you cause to other people | Required by your state, not enough on its own |
| Comprehensive | Your car if it is stolen or damaged by fire, hail, flood or vandalism | Yes, on most loans |
| Collision | Your car after a crash, no matter who caused it | Yes, on most loans |
Why Is Liability Only Not Enough?
Liability pays nothing for your own car. So when your loan needs coverage, a liability-only policy does not meet it, even if it meets your state’s minimum.
If that is what you have now, ask us first whether your loan needs full coverage. If it does, call your insurer and ask to add comprehensive and collision to your policy.
What Happens to Your Loan If Your Car Is Totaled?
A car is totaled when it would cost more to fix than it is worth. With full coverage, your insurer pays us first, and you get anything left after your loan is paid.
If the payment is less than you owe, or you have no coverage, you still owe the rest of your loan.
When Might We Approve a Title Loan Without Full Coverage?
Sometimes. It depends on your situation and on how much risk your loan carries if it is not repaid. We look at:
- How much you borrow compared with what your car is worth
- How many payments your loan has
- Your state’s law
- Your car’s value and condition
- Your income to repay the loan5
For example, borrowing $1,000 on a car worth $10,000 carries less risk than borrowing $7,000 on the same car, so the smaller loan may be easier to approve without full coverage. These numbers are only an example, not a limit.
Without full coverage, we both take a bigger risk. If your car is totaled, it no longer backs your loan, and you still owe every payment.
Does Your State Require Car Insurance?
Yes. Every state where we make title loans requires liability insurance to drive, but full coverage is our requirement, not the law.
What Must Your Insurance Policy Show?
Before you sign, we check that your policy shows:
- Your name as a named insured, which means the policy covers you by name, not only as a driver
- Your car’s VIN, the 17-character vehicle number on your title
- Comprehensive and collision coverage
- A deductible of $1,000 or less on each
- 5 Star Car Title Loans™ as loss payee
- Coverage that is active on the day you sign
As proof, send a binder, which is temporary proof of coverage, your declarations page, which is the policy’s summary page, or the full policy.
We cannot accept the insurance ID card, because it does not show your coverage, deductibles or loss payee.
What Is a Loss Payee?
A loss payee is the company your insurer pays first if your car is stolen or totaled. On your title loan, that company is us.
We are also the lienholder, which means our name stays on your car’s title until your loan is paid in full.
This is standard when you borrow against a car. A company that lends against your car will likely ask to be listed on your policy, says the Oklahoma Insurance Department.
We send you our exact loss payee name and address. Give them to your insurer, and they add us to your declarations page.
When your loan is paid in full, we release our lien on your title. Then call your insurer and ask them to remove us from your policy.
What Deductible Do You Accept?
We accept a deductible of $1,000 or less on comprehensive and collision. A $500 deductible is the easiest for us to approve.
A deductible is the part of a repair bill you pay before insurance pays the rest. If yours is higher, we may ask you to lower it.
A lower deductible means you pay less out of pocket after a crash or theft, but your monthly price usually goes up, so ask your insurer for the new price first.
How Can You Get Covered and Still Get Your Loan Fast?
Apply first. We check your car’s value and your income, and once you pre-qualify, we tell you if your loan needs full coverage.
That way, you do not pay for a policy before you know you pre-qualify.
- Apply and pre-qualify. Tell us about your car and your income, and we check both. We do not run a credit check when you apply and see if you pre-qualify.
- Get full coverage, if we tell you your loan needs it. Ask your insurer for comprehensive and collision with a deductible of $1,000 or less, and give them the loss payee name and address we send you.
- Send your proof. Send the binder or declarations page with your other documents and photos of your car, so there is no in-person inspection.
- Review, sign and get your money. Once you decide to take the loan, we run a soft credit check as part of the final approval. That does not affect your FICO score.
Take your time to check the amount, APR and payment schedule, and call us with questions. When you are fully approved and sign before 2 PM local time on a business day, we send your money the same business day.8
Applying and getting your loan estimate are free, with no obligation to take the loan.3
Apply Now“The thing I see stop these loans most often is a small mismatch on the insurance paperwork: our loss payee name or address typed wrong, or a deductible above $1,000. Ask your insurance agent to email the binder or declarations page to you, not to us, and forward it to your loan officer yourself.
If something doesn’t match, don’t worry. Call your insurer, ask for an update to the loss payee details or the deductible, and send us the new page.”
Bryan Solis
Head of Underwriting, 5 Star Car Title Loans™
What If Your Insurance Situation Is Different?
Most insurance problems have a quick fix, and you can still apply first.
Is the Policy in Someone Else’s Name?
Being only a listed driver on a parent’s or spouse’s policy is not enough. The person on the title needs to be a named insured.
To fix it, buy your own policy for this car, or ask the policyholder, the person who owns the policy, to add you as a named insured if you live together.
Can You Use an SR-22 or High-Risk Policy?
Yes, if it is an owner’s policy for this car with comprehensive and collision. A non-owner SR-22 cannot be used, because it does not cover a specific car.
An SR-22 is a form your insurer files with the state to prove you carry insurance, often after a license suspension, says the Virginia DMV. A high-risk policy is insurance for drivers with past tickets, crashes or gaps in coverage.
Did Your Insurance Lapse Before You Applied?
You can still apply. A lapse means your policy stopped, often because a payment was missed or it was not renewed.
If your loan needs full coverage, ask your insurer to turn your old policy back on or buy a new one, and send us the new proof before you sign.
What Happens If Your Insurance Stops During the Loan?
If your policy is canceled or lapses, your insurer tells us. We contact you first and give you time to send new proof.
This is usually about 30 days, but it can differ with your state’s law and your loan agreement.
If your coverage is about to end, call us first. We can tell you what your policy needs before anything is added to your loan.
What Is Force-Placed Insurance?
Force-placed insurance is a policy we may buy on your car if yours stops and no new proof comes, and we add its cost to your loan.
We do this only where your state’s law allows. Some states, such as Florida and Virginia, do not allow it.
The Consumer Financial Protection Bureau says it protects only the lender, not you, and usually costs a lot more than a policy you buy yourself. It is not the liability insurance your state requires to drive.
When you send proof of your own full coverage, we cancel it.
What If You Also Fall Behind on Payments?
If you fall behind on payments, your loan can go into default, and we can repossess your car, which means take it back, and sell it under your state’s law.9 If the sale does not cover what you owe, you may still owe the rest where your state’s law allows.
Our guide to title loan repossession explains your rights.
Frequently Asked Questions
Can I Cancel My Full Coverage After I Get the Money?
No. If your loan requires full coverage, you need to keep it until your loan is paid in full.
If it stops, we contact you first. If no new proof comes, we may add force-placed insurance to your loan where your state’s law allows, and it usually costs more.
Is a Title Pawn the Same as a Title Loan?
Yes, at a title loan company like ours, a title pawn and a title loan are the same thing. You borrow against your car’s title.
Some pawn shops may keep your car until you repay. With us, you keep driving it.
What Else Do I Need Besides Insurance?
You need the title in your name, a driver’s license, state ID or passport, proof you can make the payments, proof of address and photos of your car.
Our title loan requirements explain each one.
Questions about your insurance before you apply? Call us, and we will tell you what your loan needs.


