
Yes. You can get a title loan from us without a checking or savings account. You just need to meet our approval requirements and show proof of steady income when you apply.5
At 5 Star Car Title Loans, without a bank account:
- Our borrowers with no bank account: about 20% to 30%, based on our 2024 to 2025 data
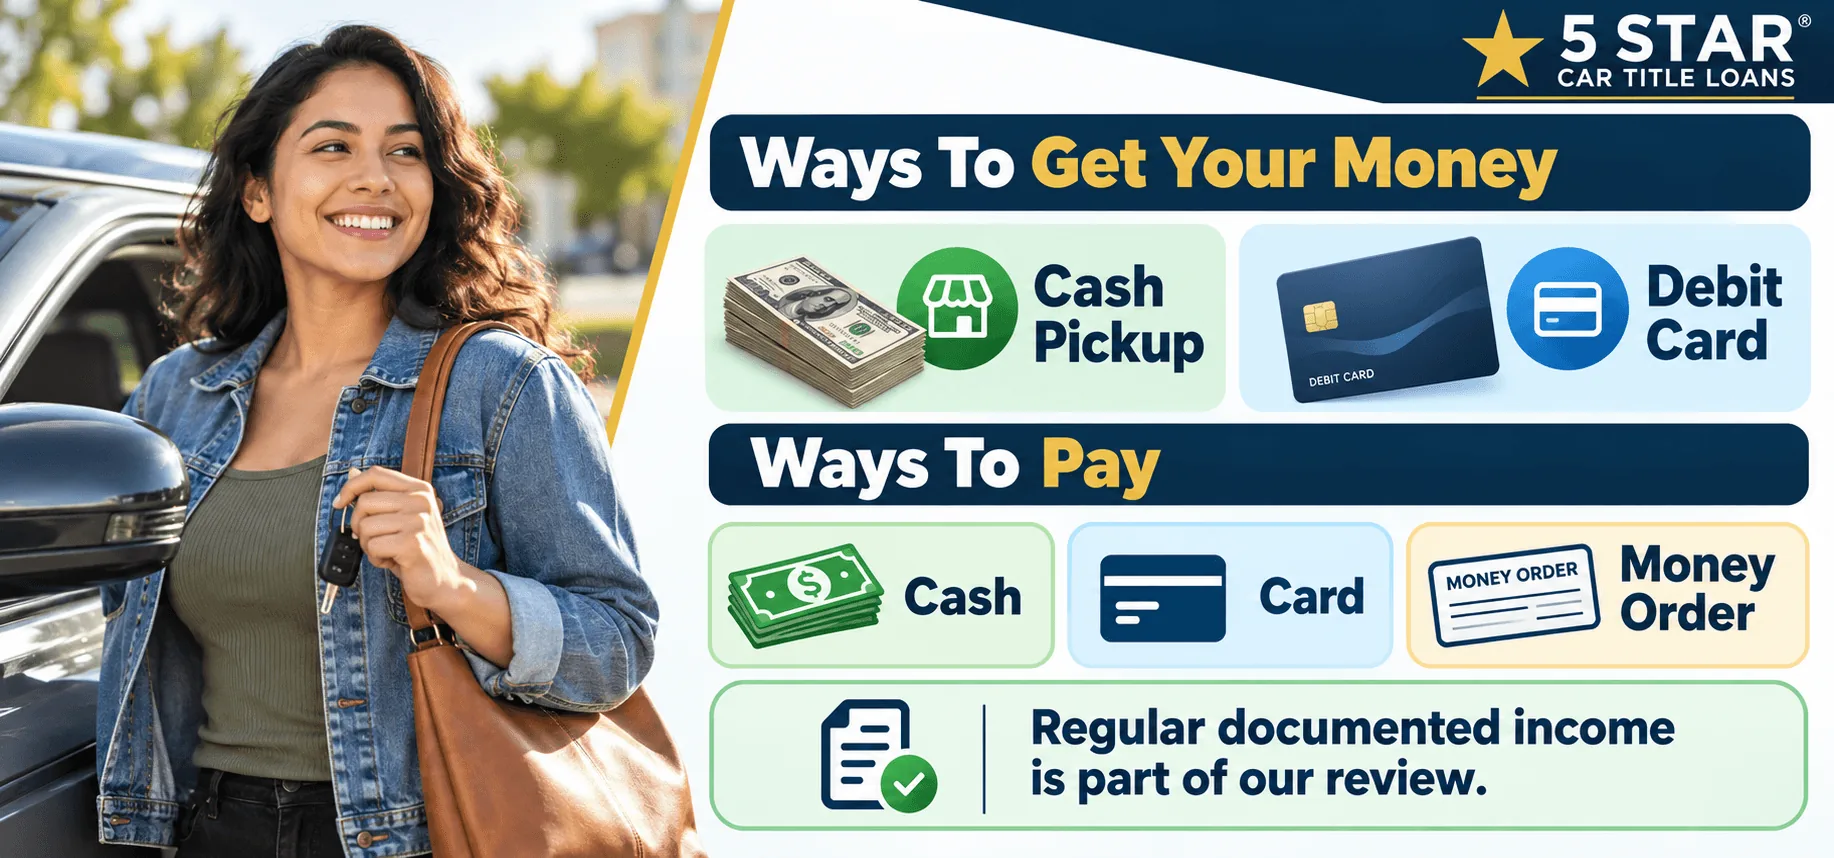
- Get your money: MoneyGram cash pickup or a debit card
- Pay it back: cash, a prepaid card or a money order
- Prove income: an employer letter, benefit letter, tax return or app statements
- Our median loan, all borrowers: $3,000, for loans funded January 2024 to December 20256
Editorial Disclosure: 5 Star Car Title Loans™ is a licensed direct lender, NMLS ID 2253575. This guide is for informational purposes only and is not financial advice. Your loan approval, amount, APR and terms depend on your state’s law, your car and your income.
Why Can You Get a Title Loan Without a Bank Account?
A title loan does not require a bank account because the loan is secured by your vehicle, not by money in a checking or savings account.
We look at your vehicle’s value and available equity, along with your ability to repay, when deciding whether to approve your loan.6
You can also get your money and pay it back without having a checking or savings account. We send it as MoneyGram cash or to your debit card, and you pay us back in cash, by card or by money order.
In its 2017 rule on these loans, the CFPB wrote: “Unlike payday loans, there is generally no requirement that the borrowers have a bank account.”
How Do You Prove Income Without Bank Statements?
You can use other documents that show you have steady income to repay your loan. What we ask for depends on how you get paid:5
- Paid in cash: a signed letter from your employer, or your latest tax return if you are self-employed
- Paid through Cash App or Venmo: the app’s official monthly statements, not screenshots
- Benefits on a card like Direct Express: your Social Security or VA benefit letter. You can download your Social Security letter online.
Our guide to title loans with other proof of income lists every kind of income we accept and the papers for each.
What Else Do You Need to Apply?
Besides proof of income, you need:
- Title: the car title in your name
- ID: a driver’s license, state ID or passport
- Insurance: proof of active coverage, the policy or the declarations page
- Address: proof of where you live
- The car: in person or by photos
You do not need your registration, a spare key, references or a co-signer. If you do not have a Social Security number, you can use an ITIN instead.
Our guide to title loan requirements covers each item.
How Do You Get the Money Without a Bank Account?
You can get your money two ways: as cash from a MoneyGram counter, or sent to your debit card.
Option 1: MoneyGram Cash Pickup
We send the loan amount digitally. You walk into a retail MoneyGram location, like one inside Walmart or CVS, and collect the cash.
Bring: a valid government photo ID and your reference number.
You can pick it up within an hour of approval, during the store’s opening hours.8
Option 2: Debit Card Transfer
If you have a standalone Visa or Mastercard debit card, like a prepaid card or a digital bank card, we push the money straight to that card number.
The money typically arrives on your card within 30 minutes after you sign your title loan agreement. Timing depends on the bank behind your card, and not every card can receive it.8
Does It Cost Anything to Get Your Money?
If you choose MoneyGram pickup, we pay MoneyGram’s transfer fee upfront so the money can be sent. We then pass that cost on to you, taken from your loan amount.
For example, MoneyGram’s online fee check showed a $25 fee to send $3,000 within the U.S. in October 2026.
If you are approved for $3,000 and that fee comes out of it, you collect $2,975 in cash at the counter. Your offer shows the exact fee before you sign.
How Do You Pay Back Your Title Loan Without a Bank Account?
You have four ways to pay, and none of them needs a bank account:
- Cash at Bank of America: deposit it at any branch
- Card, online or by phone: prepaid and benefits cards like Green Dot, Netspend and Direct Express work on the Visa or Mastercard network, with no fee from us
- Cash at MoneyGram: pay at a bill-pay counter, where MoneyGram charges its own fee of about $1.99 to $12.99
- Money order by mail: with your loan number on it
Our How to Pay page has the account details, phone number and mailing address.
How to Get a Title Loan Without a Bank Account, Step by Step
- Apply online or by phone. Tell us about your car and your income. When the form asks about a bank account, answer no and pick how you want to get your money. You see in minutes if you pre-qualify, with no credit check.8
- Send your documents and car photos. Send your ID, title, insurance, proof of address and photos of your car. Instead of bank statements, send other proof of income that shows you can repay. You may qualify for about 25% to 50% of your car’s equity, subject to your state’s law.6
- Review and sign your offer. Your offer shows the amount, APR, payments and term. Take your time, and call us with any questions before you sign.
- Get your money and keep driving. Collect your cash at MoneyGram with your ID and reference number, or check your debit card.8 You keep driving your car while you repay, and we release the lien when the loan is paid off.
To see the full process, from your application to getting your title back, read how our title loans work.
Applying and getting your loan estimate are free, and you have no obligation to take the loan.3
Apply NowWhat About My Credit, the Cost and the Risk?
Will You Check My Credit?
Not to pre-qualify. We do not run a credit check when you apply and see if you pre-qualify.
Once you decide to take the loan, we run a soft credit check as part of the final approval. That does not affect your FICO score.
Will This Loan Build My Credit?
No. We do not report your loan or your on-time payments to Equifax, Experian or TransUnion, so paying on time will not raise your score.
We do not report routine late payments either. If you default and we take a loss after repossessing and selling the car, or your balance goes to a collection agency, a negative mark can end up on your credit report.
How Much Does a Title Loan Cost?
Title loans are expensive. The FTC guide notes that title loans “often have monthly finance fees as high as 25%, which translates to an APR of about 300%.”
Our APRs go up to 150%, and never above the cap your state’s law sets. Our guide to car title loan interest rates shows what that means in monthly payments.7
What Happens If I Fall Behind?
If you think you will miss a payment, call us first. We may be able to find a solution with you, such as refinancing your current loan with more flexible payments.
If you stop paying, the loan goes into default, and we can repossess and sell the car under your state’s law.9 If the sale does not cover what you owe, you may still owe the rest where your state’s law allows it, and the balance can go to a collection agency.
Our guides to refinancing a title loan and title loan repossession explain each step and your rights.
Frequently Asked Questions
Can I Get a Title Loan if I Don’t Have Direct Deposit?
Yes. We do not need direct deposit. You can take your money as MoneyGram cash or on a Visa or Mastercard debit card.
Can I Get My Loan on a Prepaid Card?
Yes, as long as it is a Visa or Mastercard debit card, which many prepaid and digital bank cards are.
You can use the same card to make your payments online or by phone.
Can I Get a Loan From a Bank With No Bank Account?
Usually not. Banks and credit unions typically want you to open an account with them first, because that is where they send the money and collect payments.
What Disqualifies You From Getting a Title Loan?
The most common reason is a car worth too little for the amount you asked for, which usually means a smaller loan. Other reasons include not being an owner on the title, a title name that does not match your ID, no way to show income or an expired ID.
Not having a bank account is not on the list.
Can I Get a Title Loan With No Bank Account and Bad Credit?
You may still qualify. Your car’s value and whether you can afford the payments count more than your credit score.
A title loan is one option for borrowers with bad credit and no bank account. Our guide to title loans for bad credit explains more.
Is It Smart to Use My Car as Collateral?
Your car secures the loan, so if you cannot repay, you could lose it.
Before you apply, ask yourself: Can I make every payment on time? Is this for an emergency? Do I have a cheaper option?
Our guide Is a Title Loan the Right Choice for You? walks through these questions.


